Introduction
Markets rarely remain stable for long. Changes in customer expectations, technological advancements, economic conditions, and competitive pressures can quickly reshape how businesses operate and deliver value. Organisations that rely solely on established practices may struggle to maintain their market position as conditions change. In contrast, businesses that recognise emerging trends and respond strategically are better positioned to protect their competitiveness and pursue new growth opportunities.
Understanding how businesses can adapt to changing markets is essential for long-term success. Adaptation involves more than reacting to immediate challenges; it requires companies to evaluate their business models, understand customer needs, embrace innovation, and make informed decisions about future investments. By developing a flexible, forward-looking approach, organisations can navigate uncertainty while staying focused on their strategic objectives.
Why Businesses Must Adapt to Changing Markets
Market changes influence nearly every aspect of business operations, from product development and pricing to marketing strategies and supply chain management. Consumer preferences may shift toward more convenient services, competitors may introduce disruptive technologies, or economic pressures may change purchasing behaviour. Businesses that overlook these developments risk losing customers and weakening their competitive advantage.
For example, a traditional retailer that relies entirely on physical stores may struggle as customers increasingly prefer online shopping. Rather than abandoning its existing operations immediately, the retailer could introduce an e-commerce platform, offer convenient delivery options, and use customer data to improve product recommendations. This approach allows the company to respond to changing shopping habits while preserving the value of its existing business.
Adaptation also helps businesses identify opportunities that emerge during periods of uncertainty. Changes in consumer behaviour can create demand for new products, while technological developments can improve productivity and reduce operational costs. Companies that monitor these shifts can adjust their strategies before emerging challenges become more difficult to manage.
According to strategic management principles, successful adaptation requires organisations to align their capabilities with external market conditions rather than relying solely on past performance. Research on adapting to market shifts similarly emphasises understanding market dynamics, evaluating business models, and prioritising customer relationships.
1. Monitor Market Trends and Understand Customer Needs
The first step in adapting to changing markets is to develop a clear understanding of what is happening outside the organisation. Businesses should regularly assess industry developments, competitor activities, economic indicators, technological changes, and evolving customer expectations. Market research provides valuable information for identifying these changes. Customer surveys, sales reports, online reviews, social media discussions, and direct conversations with clients can reveal emerging preferences and recurring problems. Competitor analysis can also help organisations identify market gaps and opportunities to differentiate their offerings.
However, collecting information is only useful when businesses translate it into actionable insights. For example, a decline in sales might reflect changing customer preferences, an unsuitable pricing strategy, stronger competition, or reduced purchasing power. Each possibility requires a different response. We recommend establishing a consistent process to review market information and identify meaningful patterns. By distinguishing temporary fluctuations from lasting trends, businesses can make more informed decisions and avoid unnecessary changes based on isolated events.
2. Develop a Flexible Business Strategy
A business strategy provides direction, but it should not prevent an organisation from responding to new circumstances. Effective strategic planning establishes clear long-term objectives while allowing flexibility in how those objectives are achieved. Businesses can start by reviewing their business model, revenue sources, cost structure, customer segments, and distribution channels. This assessment helps identify which activities remain effective and which require adjustment. Leaders can then establish alternative plans for different market scenarios, including slower demand, increased competition, or unexpected supply disruptions.
For example, a company that relies heavily on one customer segment may face significant financial pressure if that segment experiences an economic downturn. Expanding into additional customer groups or developing complementary services could reduce this dependence and create more balanced revenue opportunities.
Flexible planning also requires clear decision-making processes. Businesses should define measurable objectives, assign responsibility for strategic initiatives, and regularly evaluate results. When performance differs significantly from expectations, management can investigate the underlying causes and revise the plan where necessary. The objective is not to change direction constantly. Instead, businesses should preserve their core strengths while staying prepared to adjust their approach when reliable evidence shows a change is necessary.
3. Embrace Innovation and Digital Transformation
Innovation allows businesses to respond to changing expectations, improve efficiency, and create new sources of value. It does not always require developing entirely new products or investing heavily in advanced technology. Often, small improvements to existing processes can produce meaningful results.
Digital transformation is one important way organisations can adapt. Businesses can use customer relationship management systems to organise client information, analytics tools to evaluate sales performance, and automation to reduce repetitive administrative tasks. E-commerce platforms and digital marketing channels can also help companies reach customers beyond their traditional geographical markets.
Consider a consulting firm that previously relied on manual reporting and fragmented communication. By adopting collaborative project management software, standardised reporting processes, and automated administrative workflows, the firm could improve coordination and provide clients with more consistent service.
Nevertheless, technology adoption should begin with a clearly identified business need. Buying software without understanding the problem it is meant to solve can raise costs without delivering meaningful improvements. Businesses should evaluate the expected benefits, implementation requirements, employee training needs, and potential risks before committing resources. A disciplined approach to innovation lets companies experiment, measure results, and scale successful initiatives without exposing the organisation to unnecessary financial or operational risks.
4. Strengthen Customer Relationships and Improve Value
Customers are central to adapting successfully to the market. As their expectations evolve, businesses must continually assess whether their products, services, pricing, and customer experiences remain relevant. One effective approach is to establish regular feedback mechanisms. Businesses can use customer interviews, satisfaction surveys, purchase patterns, and support requests to identify areas requiring improvement. These insights can guide product adjustments, service enhancements, and more relevant marketing communications.
Personalisation can also improve customer experiences when it is based on appropriate and responsibly managed customer information. For instance, a company may recommend products based on past purchases or offer service packages that meet different customer needs. However, businesses should avoid assuming that every customer wants the same experience. Some customers prioritise affordability, while others value convenience, reliability, customisation, or premium quality. Understanding these differences allows companies to develop offerings that match their intended market segments.
Customer relationships also depend on trust. Clear communication, consistent service quality, transparent pricing, and responsive support can help businesses maintain customer confidence during periods of change. When companies introduce new products, policies, or pricing structures, explaining the reasons behind those decisions can reduce confusion and strengthen long-term relationships.
5. Build Operational Flexibility and Resilience
Adapting to market changes requires more than an effective marketing strategy. Businesses must also ensure that their internal operations can respond to fluctuations in demand, supply availability, costs, and workforce requirements. Businesses can strengthen operational flexibility by reviewing supply chain dependencies, improving inventory management, cross-training employees, and identifying alternative suppliers. These measures can reduce disruption from unexpected events and help organisations maintain essential services.
Financial resilience is equally important. Businesses should monitor cash flow, manage debt carefully, assess operating expenses, and, where feasible, maintain appropriate financial reserves. A company with limited financial flexibility may struggle to invest in new opportunities or withstand a temporary decline in revenue.
For example, a manufacturer that depends on a single supplier may face production delays if that supplier has problems. Developing relationships with alternative suppliers and identifying critical materials in advance can reduce this vulnerability. Although diversification may increase some procurement costs, the additional flexibility can be valuable when disruptions occur. Resilience does not mean eliminating every possible risk. Instead, it involves identifying the risks that could materially affect business performance and developing proportionate measures to manage them.
6. Invest in Employees and Adaptive Leadership
Employees play a critical role in helping organisations respond to market changes. New technologies, customer expectations, and operating models often require different skills and ways of working. Businesses that invest in employee development are better equipped to implement changes effectively. Training programs can help employees develop digital skills, analytical capabilities, communication techniques, and problem-solving abilities. Managers should also encourage teams to share observations from daily operations because employees who interact directly with customers and suppliers may recognise emerging issues before they become visible in management reports.
Adaptive leadership is equally important. Leaders need to communicate the purpose of organisational changes, set realistic expectations, and provide employees with the resources they need to succeed. They should encourage constructive feedback and treat unsuccessful experiments as learning opportunities, as long as risks are managed responsibly. A workplace culture that supports continuous learning can help businesses respond more effectively to unfamiliar challenges. Rather than treating established procedures as permanent, employees can identify improvements while maintaining accountability, quality standards, and regulatory compliance.
7. Measure Performance and Adjust Strategies Continuously
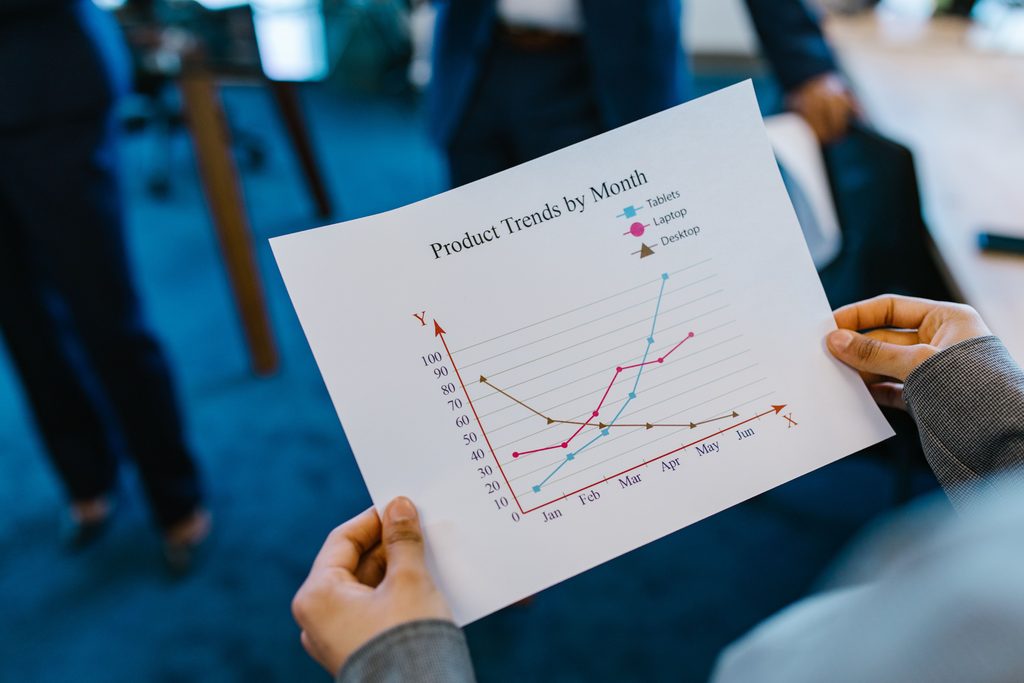
Business adaptation should be evaluated through measurable outcomes rather than assumptions. Without clear performance indicators, organisations may invest in initiatives that seem promising but fail to improve results. Relevant key performance indicators (KPIs) may include revenue growth, customer retention, customer acquisition costs, profit margins, inventory turnover, employee productivity, and customer satisfaction. The best indicators depend on the organisation’s objectives, industry, and current challenges.
Businesses should establish a baseline before implementing major changes. They can then compare subsequent performance against that baseline to determine whether the initiative is producing the intended results. For example, a company introducing an online sales channel could monitor conversion rates, order fulfilment costs, repeat purchases, and revenue generated through the new channel.
Regular performance reviews help management distinguish successful initiatives from those that require modification. They also create opportunities to reallocate resources toward activities that deliver stronger results. Continuous evaluation matters because market conditions rarely stay the same. A strategy that works today may require adjustment as customer expectations, technologies, and competitive dynamics evolve.
How Businesses Can Turn Market Changes Into Growth Opportunities
Adapting to changing markets isn’t just about protecting a business from disruption. It can also help organisations discover new revenue streams, improve customer experiences, enter additional markets, and strengthen their competitive positioning. To achieve these outcomes, businesses should connect market research, strategic planning, innovation, operational management, and performance measurement within a consistent decision-making framework. Each function contributes different information, but the greatest value comes when these insights inform a coordinated business strategy.
Organisations should also recognise that not every market trend deserves an immediate response. Some developments may be temporary, while others may require investments beyond the company’s current capabilities. Evaluating market relevance, financial feasibility, implementation risks, and alignment with long-term objectives helps leaders prioritise the most promising opportunities. Strategic adaptation therefore balances responsiveness and discipline. Businesses must remain open to change without losing sight of their core purpose, customer value proposition, and financial sustainability.
Conclusion
Understanding how businesses can adapt to changing markets is fundamental to building a competitive, resilient organisation. By monitoring market trends, developing flexible strategies, embracing appropriate technologies, strengthening customer relationships, and investing in employees, businesses can respond more effectively to evolving conditions. Long-term success depends on continuous management rather than occasional reactions to disruption. Through regular performance evaluation, thoughtful resource allocation, and informed decision-making, organisations can manage uncertainty while identifying opportunities for sustainable growth.
At Solutionariez, we recognise the importance of aligning business strategy with changing market realities. A structured approach to strategic planning and organisational improvement helps businesses assess their current position, identify areas for development, and make decisions that support their long-term objectives. Companies that combine strategic clarity with the willingness to evolve are better prepared to remain relevant in an increasingly dynamic business environment.


